 Emergency Call
 Monday to Friday - 08:00 - 20:00


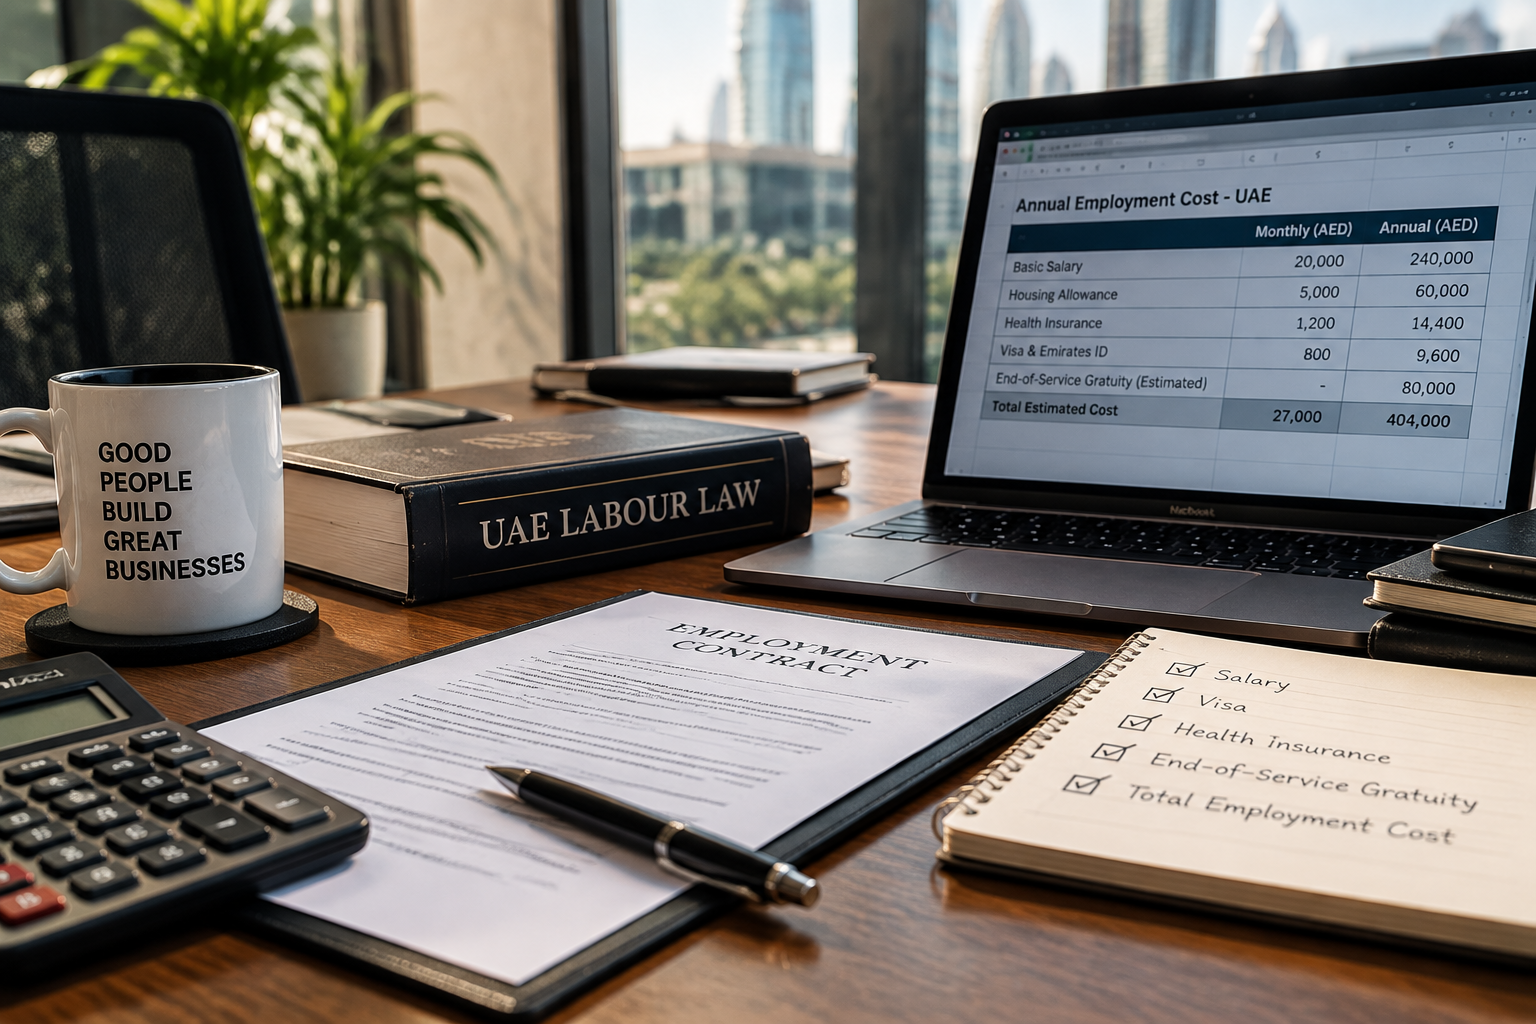
A UK business owner hiring their first employee in the UAE will usually think about the obvious costs first: salary, visa expenses, health insurance, office costs and payroll.
But there is another employment liability that can catch UK employers completely off guard: UAE end-of-service gratuity.
There is no direct equivalent to the UAE system in UK employment law.
Unlike UK statutory redundancy pay, which is generally associated with redundancy and has specific eligibility and statutory limits, UAE end-of-service gratuity is a statutory employment benefit that can become payable when an eligible employee's employment ends.
For private-sector foreign workers, the UAE Government states that employees who complete at least one year of continuous service are generally entitled to gratuity, with the calculation based on basic salary rather than the employee's full remuneration package.
For a UK business expanding into the UAE, this means gratuity should not be treated as an unexpected payment at the end of an employee's employment.
It should be treated as a running employment liability from the beginning.
This guide explains how UAE end-of-service gratuity works in 2026, how to calculate it, what salary components count, how it compares with UK redundancy pay, and what UK employers should do to budget for it properly.
The UK Concept That Doesn't Exist: Why Gratuity Catches UK Employers Out
For many UK employers, the natural assumption is that an employee leaving the business simply receives:
-
Their final salary
-
Any applicable notice pay
-
Accrued but unused holiday
-
Statutory redundancy pay, where applicable
The UAE framework works differently.
End-of-service gratuity is a statutory entitlement for eligible private-sector employees who complete the required period of service. The UAE Government confirms that a foreign worker who has completed at least one year of continuous service is generally entitled to gratuity when employment ends.
That means a UK business owner cannot simply budget for the employee's monthly salary and assume that is the full employment cost.
There may also be an accumulated gratuity liability sitting in the background.
And the longer an employee remains with the business, the larger that liability can become.
Why this matters for UK employers
Consider a UAE employee earning AED 20,000 per month.
If the employee remains with the company for several years, the employer may eventually owe a substantial gratuity amount when employment ends.
That liability should therefore be considered when:
-
Setting employee budgets
-
Structuring salary packages
-
Preparing management accounts
-
Forecasting cash flow
-
Valuing a UAE business
-
Planning an acquisition or restructuring
-
Closing or selling a UAE entity
The mistake isn't failing to understand the formula.
The mistake is not accounting for the liability until the employee leaves.
What Is UAE End-of-Service Gratuity?
UAE end-of-service gratuity is a statutory benefit payable to eligible employees when their employment relationship ends.
For employees covered by the standard UAE private-sector Labour Law framework, gratuity is generally calculated using:
Basic salary × applicable number of days × years of service
The UAE Government confirms that:
-
Employees with less than one year of continuous service generally receive no gratuity.
-
Employees with more than one year but less than five years receive 21 days' salary for each year of service.
-
Employees with more than five years receive 21 days for each of the first five years and 30 days for each subsequent year.
-
Partial years are calculated proportionately once the employee has completed the one-year minimum.
-
Total gratuity is capped at two years' wages.
Importantly, gratuity is based on basic salary, not the employee's entire monthly package.
That distinction can have a significant impact on the final liability.
Who Is Entitled to UAE Gratuity?
The standard UAE private-sector gratuity rules generally apply to eligible employees who have completed at least one year of continuous service.
The UAE Government specifically states that days of unpaid absence are excluded when calculating the period of service.
Employees with less than one year
An employee who has not completed one year of continuous service generally does not qualify for statutory gratuity under the standard formula.
Employees with more than one year
Once the one-year minimum is satisfied, gratuity is calculated according to the applicable formula, including proportionate treatment for part-years.
Resignation vs termination
One of the biggest differences UK employers need to understand is that gratuity should not be thought of as simply a redundancy payment.
An employee's entitlement can arise when employment ends through resignation or termination, subject to the applicable Labour Law provisions and circumstances.
The UAE Government's employment guidance confirms that employment may be terminated by either party subject to the applicable legal requirements and notice provisions.
This is why UK employers should not build their UAE payroll model around the assumption that gratuity only becomes relevant when the company dismisses an employee.
How UAE Gratuity Is Calculated in 2026
The standard calculation is relatively straightforward.
For the first five years
The employee receives:
21 days of basic salary for each year of service
After five years
The calculation becomes:
30 days of basic salary for each additional year of service
The total gratuity cannot exceed the equivalent of two years' wages.
Basic daily salary
For a monthly-paid employee, the calculation can generally be illustrated using:
Monthly basic salary ÷ 30 = daily basic salary
The applicable 21 or 30 days is then multiplied by the relevant years of service.
Example
An employee has:
-
Basic salary: AED 12,000
-
Service: 3 years
Daily basic salary:
AED 12,000 ÷ 30 = AED 400
Gratuity:
AED 400 × 21 days × 3 years = AED 25,200
So the employee's estimated gratuity entitlement would be:
AED 25,200
Worked UAE Gratuity Examples
Example 1: Three Years of Service
An employee earns:
Basic salary: AED 12,000
They complete:
3 years of service
Daily basic salary:
AED 12,000 ÷ 30 = AED 400
Gratuity:
21 × AED 400 × 3
= AED 25,200
Example 2: Seven Years of Service
The employee earns the same AED 12,000 basic salary but completes seven years.
The first five years:
21 × 5 × AED 400
= AED 42,000
The remaining two years:
30 × 2 × AED 400
= AED 24,000
Total:
AED 66,000
So the employer would have an estimated gratuity liability of:
AED 66,000
before considering any other final settlement amounts or applicable adjustments.
Example 3: One Year and Eight Months
Suppose an employee completes:
1 year and 8 months
with a basic salary of AED 12,000.
Because the employee has passed the one-year minimum, the additional period is calculated proportionately rather than simply being ignored. The UAE Government confirms that fractions of a year are taken into account once the one-year continuous-service requirement has been satisfied.
This is important for payroll teams because gratuity calculations should not simply round an employee's service down to the last completed year.
What Counts as "Basic Salary"?
This is one of the most important parts of UAE gratuity planning.
Gratuity is calculated using basic salary, rather than the employee's entire remuneration package. The UAE Government specifically confirms that allowances such as housing, transportation, utilities and furniture are not included in the gratuity calculation.
For example, imagine two employees both receive:
Total monthly package: AED 20,000
Employee A
-
Basic salary: AED 12,000
-
Allowances: AED 8,000
Employee B
-
Basic salary: AED 17,000
-
Allowances: AED 3,000
Although both employees receive AED 20,000 in total each month, their gratuity liabilities can be materially different because the calculation is based on basic salary.
This makes salary structure an important consideration when establishing employment packages.
However, employers should not treat allowances simply as a mechanism for artificially reducing statutory entitlements. Employment contracts and payroll structures should accurately reflect the actual remuneration arrangement and comply with applicable UAE employment law.
UAE Gratuity vs UK Redundancy Pay
For UK business owners, the easiest way to understand the difference is to stop thinking of UAE gratuity as simply "UAE redundancy pay."
They are fundamentally different systems.
|
|
UK Statutory Redundancy Pay |
UAE End-of-Service Gratuity |
|
Main trigger |
Redundancy |
End of employment, subject to eligibility and applicable law |
|
Minimum service |
Generally 2 years for statutory redundancy |
Generally 1 year |
|
Calculation basis |
Weekly pay, age and service |
Basic salary and length of service |
|
Resignation |
Generally no statutory redundancy payment |
Gratuity can generally arise on resignation once eligibility is met |
|
Salary cap |
Statutory limits apply |
Total gratuity capped at two years' wages |
|
Employer planning |
Usually event-driven |
Should be monitored as an ongoing liability |
UK statutory redundancy pay has its own eligibility rules and statutory limits, making it materially different from UAE gratuity.
For a UK business expanding into the UAE, the key lesson is:
Do not copy your UK employment-cost model into your UAE entity.
The UAE has its own employment, payroll and end-of-service framework.
8. Why UK Employers Should Treat Gratuity as a Running Liability
Imagine a UK-owned UAE company with six employees who have each been with the business for several years.
The company may have a substantial accumulated gratuity obligation even though nobody has left yet.
That means gratuity should be incorporated into the company's financial planning.
A practical approach is to:
1. Calculate gratuity regularly
Don't wait for an employee's resignation.
Review the estimated liability periodically.
2. Include it in management accounts
The management team should understand the accumulated employee benefit liability when reviewing the company's financial position.
3. Consider it when hiring
The true cost of an employee is more than their monthly salary.
4. Review salary structures
Because gratuity is based on basic salary, the basic/allowance split directly affects the calculation.
5. Forecast cash requirements
If several long-serving employees could leave around the same time, the resulting settlement requirement can be significant.
Don't confuse accounting provision with cash payment
Gratuity is ultimately settled when the employment relationship ends, subject to the applicable rules.
The purpose of tracking it as a liability is to make the future cost visible rather than allowing it to appear unexpectedly when an employee leaves.
DIFC and Free Zone Differences
One important issue for UK businesses is that not every UAE jurisdiction follows exactly the same employment framework.
Most UAE private-sector employers fall under the federal Labour Law framework.
However, the Dubai International Financial Centre (DIFC) operates under its own employment regime.
DIFC uses the DIFC Employee Workplace Savings (DEWS) Plan, which replaced the traditional gratuity arrangement for eligible employees and operates as a funded defined-contribution workplace savings system. DIFC describes the scheme as providing greater cash-flow certainty because end-of-service benefits are funded during employment rather than being paid as a lump-sum liability at exit.
This means a UK business setting up in DIFC should not automatically apply the standard UAE 21/30-day gratuity formula without first confirming which employment regime applies.
What about other Free Zones?
The fact that a business operates from a Free Zone does not automatically mean it has a separate gratuity system.
The applicable employment framework needs to be checked based on the jurisdiction and employee circumstances.
For most businesses outside special financial free zones such as DIFC, the federal private-sector framework remains highly relevant.
Common Mistakes UK Employers Make
Mistake 1: Assuming gratuity is the same as UK redundancy
It isn't.
UAE gratuity has its own eligibility and calculation framework.
Mistake 2: Only calculating gratuity when someone resigns
By then, the liability has already accumulated.
It should be monitored throughout employment.
Mistake 3: Using total salary instead of basic salary
Allowances are generally excluded from the statutory gratuity calculation.
Mistake 4: Ignoring partial years
Once the employee has completed the one-year minimum, qualifying fractions of a year are calculated proportionately.
Mistake 5: Forgetting the settlement deadline
The UAE Government states that employers must pay outstanding wages, other entitlements and gratuity within 14 days of termination of the employment contract.
Mistake 6: Applying federal rules automatically to DIFC employees
DIFC has its own employment framework and DEWS system.
Mistake 7: Treating gratuity as the only final payment
Gratuity is only one component of an employee's final settlement.
Depending on the circumstances, employers may also need to consider:
-
Outstanding salary
-
Notice pay or notice-period obligations
-
Unused annual leave
-
Other contractual entitlements
-
Deductions that are legally permissible
UAE employment termination rules include specific notice requirements, with the standard notice period generally falling between 30 and 90 days.
How Evolve Tax Helps
For UK business owners hiring in the UAE, payroll isn't simply about making sure employees receive their salaries on time.
The employment structure needs to account for the liabilities that build up alongside the payroll.
Evolve Tax can help with:
-
UAE payroll setup
-
End-of-service gratuity calculations
-
Monthly gratuity liability tracking
-
Employee salary structure reviews
-
WPS-related payroll compliance
-
Final employee settlement calculations
-
UAE employment cost forecasting
-
Ongoing accounting and compliance support
Our approach is designed to help UK business owners understand the full cost of employing staff in the UAE, rather than discovering additional liabilities only when an employee leaves.
Frequently Asked Questions
1. Is UAE gratuity payable when an employee resigns?
Generally, eligible employees who have completed at least one year of continuous service can be entitled to end-of-service gratuity when employment ends, including on resignation, subject to the circumstances and applicable Labour Law provisions.
2. How is UAE gratuity calculated in 2026?
For the standard private-sector framework, gratuity is generally calculated at 21 days of basic salary for each of the first five years and 30 days for each subsequent year, subject to the two-year wage cap.
3. Is gratuity calculated on the employee's full salary?
No. The standard calculation is based on the employee's basic salary. Housing, transportation and similar allowances are generally excluded.
4. Does an employee receive gratuity after one year?
Generally, an eligible employee must complete at least one year of continuous service. Once that minimum is met, qualifying partial years can also be calculated proportionately.
5. How quickly must an employer pay gratuity?
The UAE Government states that employers must settle outstanding wages, other entitlements and gratuity within 14 days of termination of the employment contract.
6. Does gratuity apply to UK nationals working in the UAE?
Eligibility is generally determined by the applicable employment framework and the employee's service, rather than simply their nationality. UK nationals employed under the UAE private-sector framework can therefore fall within the applicable gratuity rules.
Conclusion: Gratuity Is a Cost of Employment, Not Just a Cost of Leaving
For UK business owners expanding into the UAE, end-of-service gratuity is one of the easiest employment costs to underestimate.
The formula itself is relatively simple: eligible employees under the standard federal framework generally receive 21 days of basic salary for each of their first five years and 30 days for each subsequent year, subject to the applicable two-year wage cap.
The real issue is planning.
Gratuity accumulates while employees remain with the business, which means waiting until someone resigns to calculate it can turn a predictable liability into an unexpected cash-flow problem.
UK employers should therefore build gratuity into their UAE employment-cost model from the beginning. Track the liability, review basic salary structures, account for it in financial planning and understand whether a different employment regime — such as DIFC's DEWS system, applies to the business.
The best time to understand your UAE gratuity liability is before the employee leaves, not when the 14-day settlement clock starts.