 Emergency Call
 Monday to Friday - 08:00 - 20:00


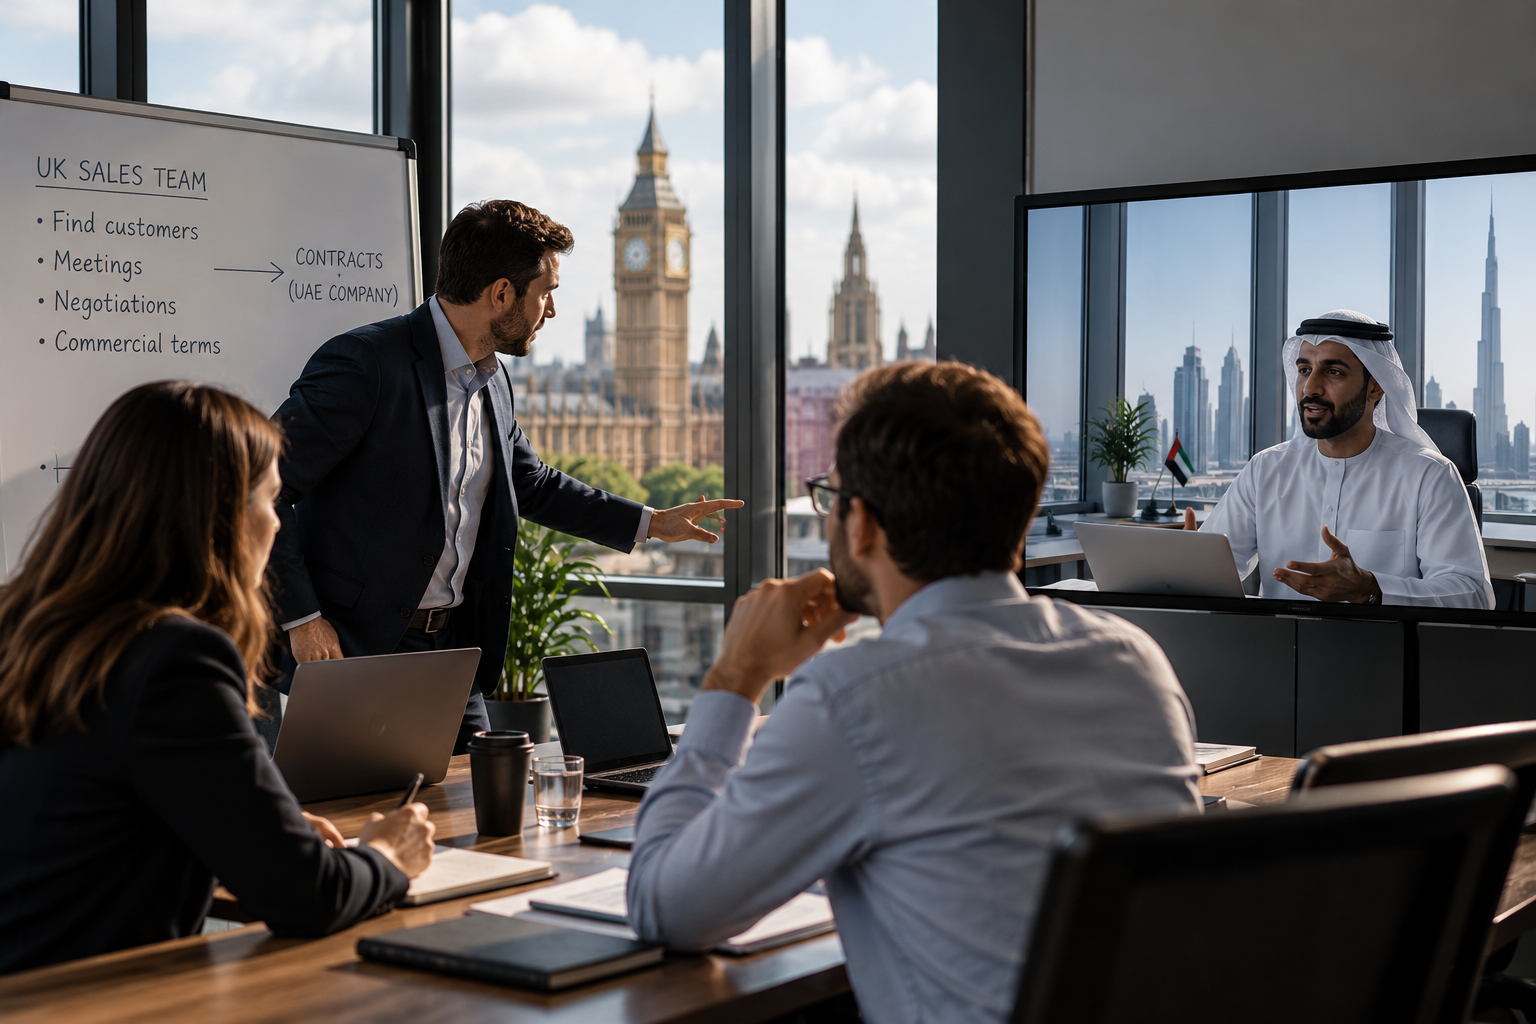
You have moved part of your business to the UAE, but your UK operation has not disappeared.
Your UAE company is now the main operating company. But your UK sales team is still finding customers, running meetings and helping bring in revenue.
The contracts may be issued by the UAE company and formally signed by someone in Dubai.
So, can that UK activity create a UK permanent establishment for your UAE company?
Yes, potentially. But having a UK sales team does not automatically create a PE.
The important question is what the UK team actually does for the UAE company.
If they are simply generating leads and passing opportunities to Dubai, that is very different from a team that negotiates the commercial deal and routinely brings contracts to the point of conclusion.
That distinction is particularly important under the UK's current domestic dependent-agent rules. GOV.UK
The Real Question Is What Your UK Team Does
A job title will not answer the PE question.
Suppose your UK employee finds potential customers, arranges meetings and introduces them to the UAE team. Pricing, negotiations and the final commercial decision all happen in Dubai.
That is one fact pattern.
Now change the role.
The UK employee finds the customer, negotiates pricing, agrees commercial terms, handles objections and takes the customer through the final stages of the deal. The UAE director then signs the contract, usually without changing what was agreed.
That is a different question.
For accounting periods beginning on or after 1 January 2026, UK domestic law can treat a person acting for a company as creating a dependent-agent PE where they habitually conclude contracts or habitually play the principal role leading to contracts that are routinely concluded without material modification by the company, subject to the relevant conditions. GOV.UK
So the analysis cannot stop at:
"Our UK salesperson cannot sign the contract."
You need to look at how the contract actually gets to the signature stage.
When UK Sales Activity Becomes More Significant
There is a meaningful difference between finding a customer and driving the transaction.
HMRC's guidance explains that the newer domestic rule can cover situations where responsibilities are shared and the person's UK activities represent the majority of the activities that directly result in the conclusion of the contract. It also notes that the activity needs to occur repeatedly rather than only in isolated cases. GOV.UK
That makes questions such as these important:
-
Who identifies the opportunity?
-
Who negotiates the price?
-
Who agrees the commercial terms?
-
Who handles the customer's objections?
-
Who has the authority to make concessions?
-
Who gets the customer ready to sign?
-
How often does the same process happen?
A UK employee who simply introduces a lead is not automatically in the same position as someone effectively carrying out the UAE company's sales function from Britain.
But a UK Sales Team Does Not Automatically Create a PE
It is important not to go too far in the other direction.
Having UK customers does not, by itself, mean that a UAE company has a UK permanent establishment. HMRC specifically distinguishes between a non-resident company trading from overseas with UK customers and one that is actually carrying on its business in the UK. GOV.UK
Likewise, having a UK employee is not an automatic PE trigger.
Broadly, you need to consider whether the UAE company's UK activities fall within a fixed-place PE or a dependent-agent PE, under the applicable domestic and treaty rules. GOV.UK
That is why the answer cannot be reduced to:
"UK employee = PE."
It depends on the facts.
Don't Ignore the UK–UAE Treaty
For a UAE company, there is another important layer: the UK–UAE Double Taxation Convention.
Article 5 of the treaty defines a PE through a fixed place of business and includes a dependent-agent provision where a person, other than an independent agent covered by the treaty, acts on behalf of an enterprise and habitually exercises authority to conclude contracts on its behalf, subject to the treaty's conditions. GOV.UK
This matters because the current UK domestic rule and the UK–UAE treaty should not simply be treated as identical tests.
The 2026 UK domestic rule includes the "principal role leading to the conclusion of contracts" concept.
The treaty's Article 5(5) uses its own wording concerning authority to conclude contracts.
So if your UAE company is relying on treaty protection, the treaty analysis needs to be considered separately rather than assuming the domestic rule and treaty test are interchangeable. GOV.UK
What About a UK Office?
Salespeople are not the only issue.
You should also consider whether the UAE company's business is being carried on through a fixed place of business in the UK.
The UK–UAE treaty's definition includes places such as a place of management, branch and office. GOV.UK
So if your UK operation has developed beyond a few sales employees, look at the practical setup.
For example:
-
Does the business have a dedicated UK office?
-
Is a particular premises regularly available to the UAE company?
-
Is substantive business activity carried on there?
-
Is the UK operation becoming a permanent part of how the company conducts its business?
You do not necessarily need a formally registered UK branch for the question to arise.
What Happens If the UAE Company Has a UK PE?
This is where the issue becomes a UK Corporation Tax question.
Under the UK–UAE treaty, where a UAE enterprise carries on business in the UK through a PE, the UK can tax the profits attributable to that PE, rather than simply taxing the company's entire worldwide profit. GOV.UK
The same principle appears in HMRC's domestic guidance for non-resident companies. The profit attribution exercise looks at the UK activities and how they fit into the company's wider business. HMRC describes the calculation using a separate-entity principle. GOV.UK
So there are actually two separate questions:
First: does the UAE company have a UK PE?
Second: if it does, what profits are attributable to that PE?
The second question can require a detailed understanding of the functions performed in the UK, the assets used and the activities carried on outside the UK. GOV.UK
A Simple Example
Imagine you moved your consulting business from the UK to a UAE company.
The UAE company now signs the customer contracts and manages delivery from Dubai.
But three UK employees remain responsible for most of the UK sales process.
They find prospects, negotiate pricing, agree the scope of projects and routinely take customers to the point where the UAE director signs the contract.
The contracts are technically signed in Dubai.
That does not automatically mean there is a UK PE.
But it also does not automatically mean there isn't one.
The UK team's actual role needs to be tested against the applicable domestic PE rules, while the UK–UAE treaty position needs to be considered separately.
If a PE exists, the next question is how much profit should be attributed to the UK activities.
What Should You Review?
If your UK sales operation stayed behind when you moved your business to the UAE, review these areas:
|
Area |
What to check |
|
Lead generation |
Who actually finds the customers? |
|
Negotiation |
Who agrees pricing and commercial terms? |
|
Decision-making |
Where are substantive decisions made? |
|
Contracts |
Who takes the customer to the point of signing? |
|
Frequency |
Does the same process happen regularly? |
|
UK premises |
Is there a fixed place through which business is carried on? |
|
UK functions |
What part of the business is actually being performed in Britain? |
|
Profit |
What activities would be attributable to a UK PE if one exists? |
This is the review that matters.
Not simply whether the UAE company has a UK address or whether the final contract is signed in Dubai.
What You Shouldn't Assume
There are three assumptions worth avoiding.
"The company is incorporated in the UAE, so the UK cannot tax it."
Incorporation in the UAE does not by itself prevent UK taxation where the relevant UK PE conditions are met.
"Our UK employees cannot sign contracts, so there is no PE."
The current UK domestic dependent-agent rules can look beyond formal signing authority to the role a person plays in leading contracts to conclusion. GOV.UK
"If there is a PE, HMRC taxes everything."
No. The UK tax analysis concerns the profits attributable to the UK PE. GOV.UK
The Practical Takeaway
If you have moved your business to the UAE but retained a UK sales operation, don't assess your PE position from the company structure alone.
Map the actual sales process.
If the UK team is mainly generating leads while substantive negotiations and decisions happen in the UAE, that is one set of facts.
If the UK team is repeatedly driving the commercial process that results in contracts, the PE analysis becomes more significant under the current UK domestic rules. GOV.UK
And because the UK–UAE treaty has its own PE provisions, you need to consider both the domestic rules and the treaty rather than assuming one automatically answers the other. GOV.UK
The question to ask is therefore not simply:
"Where is our contract signed?"
It is:
"What part of our UAE company's business is actually being carried out from the UK?"
That is the question that gives you a much clearer starting point.
How EvolveTax Can Help
If you have moved your business to the UAE but still have UK employees, sales activity or other functions in Britain, your operating structure needs to be considered alongside your UK tax position.
EvolveTax can help review the UK–UAE structure, UK activities, PE considerations and potential profit attribution so you understand the tax implications of how the business actually operates.
Frequently Asked Questions
1. Can a UAE company have UK customers without creating a PE?
Yes. UK customers alone do not automatically create a UK PE. The company's activities in the UK need to be considered. GOV.UK
2. Do UK employees automatically create a PE for a UAE company?
No. Their presence alone is not enough. Their functions and role in the UAE company's business are relevant.
3. Does signing contracts in Dubai prevent a UK PE?
No. Under the current UK domestic rules, the role a person in the UK plays in leading contracts to conclusion can be relevant even where the formal contract is concluded by the UAE company. The treaty position must also be considered separately. GOV.UK
4. If my UAE company has a UK PE, is all its profit taxable in the UK?
No. The UK tax analysis generally focuses on the profits attributable to the UK PE. GOV.UK
5. Does a UK PE require a registered UK branch?
No. A PE can arise through the applicable fixed-place or dependent-agent rules without simply equating PE with a formally registered branch. GOV.UK
6. What is the first thing a UAE business should review?
Start with the actual UK operating model: who finds customers, who negotiates, who makes commercial decisions and what activity is carried out from the UK. Those facts form the basis of the PE analysis.
Conclusion
Moving your business to the UAE does not automatically remove the UK from the tax picture.
If your UK team is still carrying out meaningful parts of the sales process, the way those activities are structured can matter. The current UK domestic rules can look beyond who formally signs a contract, while the UK–UAE treaty has its own PE provisions that need to be considered separately.
So if your UAE company still has a UK sales operation, don't assess the position from the company structure alone.
Look at what the UK team actually does, where it does it and how that activity contributes to the contracts and profits of the business.
That is the starting point for understanding whether your UK activity could create a permanent establishment and what that could mean for the company's UK tax position.